The Five-Year Wealth Roadmap: From Where You Are to Where You Want to Be (2026–2031)
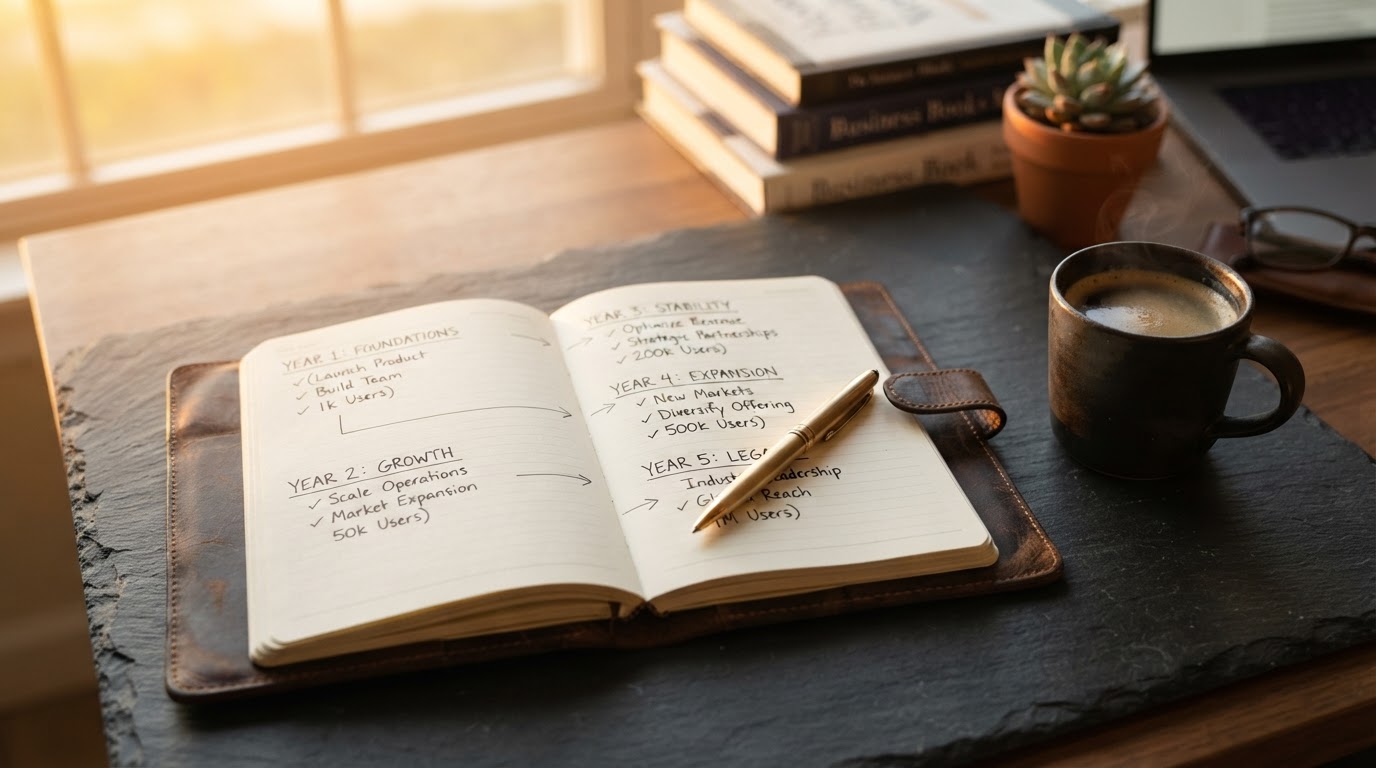
Most families never build wealth not because they lack income, but because they lack a map. They earn, they spend, they hope — and a decade passes with little to show for it beyond a bigger lifestyle and the same nagging feeling that they should be further along. The difference between families who build lasting wealth and families who don't is rarely income. It's strategy. A clear, multi-year roadmap that turns today's income into tomorrow's assets, and today's discipline into tomorrow's freedom. That's what this guide is: a five-year arc from where you are right now to where you want to be.
We're Lady Ashley Boswell and Damon Boswell, and the five-year roadmap is the framework we walk every mentee through. Five years is the sweet spot — long enough to repair credit, eliminate debt, build reserves, acquire your first assets, and see meaningful compounding, but short enough to stay focused and motivated. In this guide, Damon and I will lay out a year-by-year plan grounded in 2026 realities: the retirement contribution limits, the tax provisions, the real estate market, and the credit positioning that make each milestone achievable. Whether you're starting from debt or starting from zero, this roadmap meets you where you are and carries you toward the legacy God intended for your family.
Year One: Build the Foundation
Year one is about stabilization — fixing what's broken and building the base everything else rests on. Damon and I start every mentee in the same place: pull all three credit reports from AnnualCreditReport.com, dispute inaccuracies under the FCRA, lower credit card utilization below 10%, and begin building positive payment history. A 700+ credit score is the price of admission to every asset-based strategy that follows — real estate, business funding, premium financing — so credit repair is non-negotiable in year one. This is exactly why Damon built Express DIY Credit Repair alongside ASAP Capital Solutions: because credit and capital are two halves of the same mission.
Simultaneously, eliminate high-interest debt and build a starter emergency fund of $1,000–$2,000. Track every dollar for 30 days to understand where your money goes, then create a budget that directs 15–20% of income toward debt payoff and savings. Fidelity's saving and spending guidelines suggest putting about 50% of take-home pay toward essentials, which leaves room to direct the rest toward debt elimination and wealth-building. Lady Ashley tells every family, 'Year one isn't glamorous. It's foundational. You're pouring the concrete that the rest of the house will stand on — do it right, and everything after gets easier.'
- Pull all three credit reports and dispute inaccuracies under the FCRA.
- Lower credit card utilization below 10% and build positive payment history.
- Eliminate high-interest debt using the avalanche or snowball method.
- Build a starter emergency fund of $1,000–$2,000.
- Track every dollar for 30 days and create a 50/30/20-style budget.
- Direct 15–20% of income toward debt payoff and savings.
Principle from Damon Boswell: Year one is the concrete. Credit repair, debt elimination, and the emergency fund are the foundation everything else stands on. Skip this, and the whole structure is fragile.
Year Two: Build Reserves and Start Investing
With credit repaired and high-interest debt eliminated, year two is about building the financial buffer and beginning to invest. Grow your emergency fund to cover 3–6 months of essential expenses, held in a high-yield savings account earning 4–5% in 2026. This fund is what keeps you from reaching for credit cards when life happens — the buffer that makes your debt freedom permanent rather than temporary. Damon considers the fully funded emergency reserve the line between fragile finances and resilient finances.
Begin investing in earnest. In 2026, you can contribute up to $24,500 to a 401(k) — plus an extra $8,000 in catch-up contributions if you're 50 or older, and up to $11,250 if you're between 60 and 63. You can also contribute up to $7,500 to traditional and Roth IRAs combined. If your employer offers a 401(k) match, capture every dollar of it — that's free money and an immediate return on your contribution. For families with high-deductible health plans, an HSA lets you save up to $4,400 pre-tax for self-only coverage or $8,750 for family coverage in 2026, with an additional $1,000 catch-up if you're 55+. Lady Ashley frames it: 'Year two is when your money starts working for you instead of you working for your money. Every dollar you invest now has decades to compound — and compound growth is the quiet engine of wealth.'
- Grow the emergency fund to 3–6 months of essential expenses.
- Hold reserves in a high-yield savings account earning 4–5% in 2026.
- Contribute up to $24,500 to a 401(k) — capture the full employer match.
- Contribute up to $7,500 to traditional and Roth IRAs combined.
- Use an HSA to save up to $4,400 (self) or $8,750 (family) pre-tax.
- Begin a diversified investment portfolio in low-cost index funds.
Year Three: Acquire Your First Income-Producing Asset
Year three is where the roadmap shifts from defense to offense — from protecting and saving to acquiring assets that produce income. With credit repaired, debt eliminated, reserves built, and investments compounding, you're positioned to acquire your first real income-producing asset. For most families Damon mentors, that asset is a rental property. The 2026 market offers a genuine window for disciplined buyers: median home prices have stabilized in the $403,000–$425,000 range, rental vacancy has ticked up temporarily to around 7.1% due to a wave of new construction, and that oversupply is expected to tighten in 2026–2027 — meaning patient buyers can find cash-flowing deals today that won't exist once supply shrinks.
Before buying, run the numbers Damon teaches every investor: aim for the 1% rule (monthly rent at least 1% of purchase price), target 8–10% cash-on-cash return, maintain a DSCR of 1.4 or higher, and budget 8–10% for vacancy and 10% for capital expenditures. Conventional investment loans typically require 20–25% down and a 680+ credit score — which is why the credit repair work of year one matters so much here. For some families, the first asset is a business rather than real estate — whether built from scratch or acquired through SBA financing with as little as 10% down. Lady Ashley tells families, 'Year three is when you stop working only for money and start owning things that work for you. That's the shift from employee to steward — and it changes everything.'
Year three is when your money starts having children. The assets you acquire begin producing income of their own — and that's when wealth stops being linear and starts being exponential. — Damon Boswell
Year Four: Scale and Diversify
With your first income-producing asset established and performing, year four is about scaling what works and diversifying to reduce risk. If your first rental cash flows, use that income — plus your continued savings — to acquire a second property or to layer in a different asset class. Damon teaches mentees to build multiple streams of income in sequence rather than all at once: earned income, then investment income (dividends and interest), then asset-based income (rentals or business), then eventually residual income from intellectual property. The IRS reports that the average millionaire draws from roughly seven distinct income sources — not from greed, but from resilience.
Year four is also when tax strategy becomes critical. With the 2025 passage of the One Big Beautiful Bill Act, the 20% QBI deduction is now permanent, 100% bonus depreciation has been restored and made permanent for qualifying property, and the Section 179 expensing limit increased to $2.56 million. If you own a business or rental real estate, coordinate with a CPA to maximize these provisions — cost segregation studies on rental properties can shelter significant income in the year of acquisition. Damon models multi-year scenarios for mentees where strategic timing of depreciation, retirement contributions, and equipment purchases keeps taxable income in the optimal band year after year. Lady Ashley adds the stewardship lens: 'Year four is when strategy compounds. The structures you build now — entity, tax, diversification — determine how much of your wealth you keep and how long it lasts.'
- Scale what works — acquire a second rental or layer in a new asset class.
- Build income streams in sequence: earned, investment, asset-based, residual.
- Maximize the permanent 20% QBI deduction if you own a business.
- Use 100% bonus depreciation and Section 179 ($2.56M limit) strategically.
- Consider a cost segregation study on rental properties to shelter income.
- Coordinate with a CPA to model multi-year tax scenarios.
Year Five: Protect, Legacy-Plan, and Define Freedom
Year five is about protection and legacy — ensuring the wealth you've built survives and serves for generations. By now, you've repaired your credit, eliminated high-interest debt, built reserves, invested consistently, acquired income-producing assets, and begun diversifying. The next layer is legal protection and estate structure. Damon and I walk every family through establishing a revocable living trust to avoid probate, reviewing beneficiary designations on all accounts (these override your will), and considering whether irrevocable trusts, an ILIT, or a family limited partnership fit your situation.
Year five is also when you define what financial freedom means for your family. Damon's benchmark: when your passive and portfolio income together cover your basic living expenses, you've reached the first tier of freedom — you may still work, but you work from choice, not fear. When those streams cover your full lifestyle, you've reached full freedom. Fidelity's retirement savings target suggests aiming for 10 times your annual income by full retirement age at 67 — working backward, that's roughly 6x by age 50 and 8x by age 60. Use year five to assess where you stand against these benchmarks and adjust your trajectory. Lady Ashley tells families, 'Year five is when you stop building only for yourself and start building for the generations behind you. The trusts, the insurance, the family conversations — that's what turns wealth into legacy.'
Insight from Damon Boswell: Wealth built without protection is wealth waiting to be lost. Year five is when you build the legal containers — trusts, insurance, estate structures — that ensure your work outlasts you.
The Milestones That Mark Your Progress
A roadmap without milestones is just a wish. Damon and I give every mentee clear markers to measure progress year by year, so they know whether they're on track. These aren't rigid targets — every family's starting point differs — but they provide a compass for the journey. The most important metric, Fidelity notes, is your net worth statement — the foundation of every financial plan. Track your assets minus your liabilities annually, and watch that number grow as you execute the roadmap.
Here's the framework Damon uses: by the end of year one, credit above 700 and high-interest debt eliminated. By year two, a fully funded emergency reserve and consistent retirement contributions. By year three, your first income-producing asset cash-flowing positively. By year four, multiple income streams and an active tax strategy. By year five, legal protection in place, a defined freedom benchmark, and a net worth meaningfully higher than where you started. Lady Ashley reminds families that the milestones matter less than the direction: 'Some families move faster, some slower. What matters is that each year you're closer to freedom than the year before. Forward motion, sustained over five years, transforms a financial life.'
- Year 1: Credit above 700, high-interest debt eliminated, starter emergency fund.
- Year 2: 3–6 months in reserves, consistent retirement contributions, investing begun.
- Year 3: First income-producing asset cash-flowing positively (rental or business).
- Year 4: Multiple income streams, active tax strategy, diversified portfolio.
- Year 5: Legal protection in place, freedom benchmark defined, net worth growing.
- Track your net worth (assets minus liabilities) annually as the master metric.
The Traps That Derail a Five-Year Plan
Even the best roadmap can be derailed by predictable traps. The first is lifestyle inflation — the tendency to spend every raise rather than directing it toward assets. Damon's rule is simple: every increase in income should partly fund your next milestone, not your next lifestyle upgrade. The second is the shiny-object trap — abandoning the plan to chase a trendy investment, a speculative bet, or a 'get rich quick' scheme that promises speed but delivers risk. The third is impatience — quitting in year two or three because the results feel slow, never reaching the compounding years where the real growth happens.
Lady Ashley coaches every family through a simple filter: 'Does this decision move me closer to the year-five milestone or further from it?' If the answer is further, the answer is no — regardless of how appealing the opportunity looks. Damon adds the financial discipline: never fund a new asset with debt unless that asset's own cash flow services the debt with margin. The families who complete the five-year roadmap aren't the ones who move fastest or take the biggest risks. They're the ones who stay on the path, year after year, letting discipline and compounding do the heavy lifting that no shortcut can replicate.
The five-year roadmap rewards the faithful, not the flashy. Stay on the path, let compounding work, and you'll arrive at a place no shortcut could have taken you. — Lady Ashley Boswell
The Kingdom Dimension: Stewardship Across Time
For Damon and me, a five-year roadmap is ultimately a stewardship conversation stretched across time. Luke 16:10 tells us that whoever is faithful with little will also be faithful with much, and whoever is dishonest with little will also be dishonest with much. The five-year plan is the practice ground for that faithfulness — learning to steward a little well so that you can be entrusted with much. Each year of the roadmap is an act of stewardship: repairing what's broken, building what's absent, protecting what's gained, and passing on what's built.
When a family commits to a five-year arc of disciplined wealth-building, something deeper happens than a net worth increase. They develop the character, the patience, and the wisdom that wealth requires to be sustained. They learn to delay gratification, to resist shortcuts, to make decisions aligned with values rather than impulses. And by year five, they're positioned not just with assets but with the stewardship capacity to manage those assets for purposes bigger than themselves — funding ministries, blessing generations, and building a legacy that honors God. Damon and I teach every family that the goal of the five-year roadmap was never just to arrive at a number. The goal is to become the kind of steward who can carry the wealth God entrusts to you — and that kind of steward is built one faithful year at a time.
Principle from Damon Boswell: Whoever is faithful with little will be faithful with much. The five-year roadmap is the practice ground for that faithfulness — stewarding a little well so you can be entrusted with much.
Your Next Step: Draw Your Map
If you've been earning and spending without a clear map, this is your invitation to draw one. Start by assessing where you are right now — your credit, your debt, your reserves, your assets, your net worth. Then map the five-year arc: what needs to happen in year one to build the foundation, in year two to invest and reserve, in year three to acquire your first asset, in year four to scale and diversify, and in year five to protect and legacy-plan. Write it down. Review it annually. Adjust as life changes, but never abandon the direction. Five years from now, you'll either be glad you started today or wishing you had.
Through Express DIY Credit Repair, ASAP Capital Solutions, and the mentorship Lady Ashley Boswell and I provide together, Damon Boswell helps families build and execute five-year wealth roadmaps — from credit repair and debt elimination to real estate, tax strategy, and legacy planning. If you're ready to stop drifting and start building — with a clear map, with strategy, with stewardship, and with a guide who's walked this road — we'd be honored to help. Book a call and let's draw your five-year roadmap together. Because the family God entrusted to you deserves a future built on intention, not accident — and that future begins with a map drawn today.
Ready to Build Your Wealth Roadmap?
Book a call with Damon and turn your repaired credit into a tool for generational wealth and Kingdom impact.
Book a Call