HELOC Strategy: How to Put Your Home Equity to Work Building Wealth in 2026
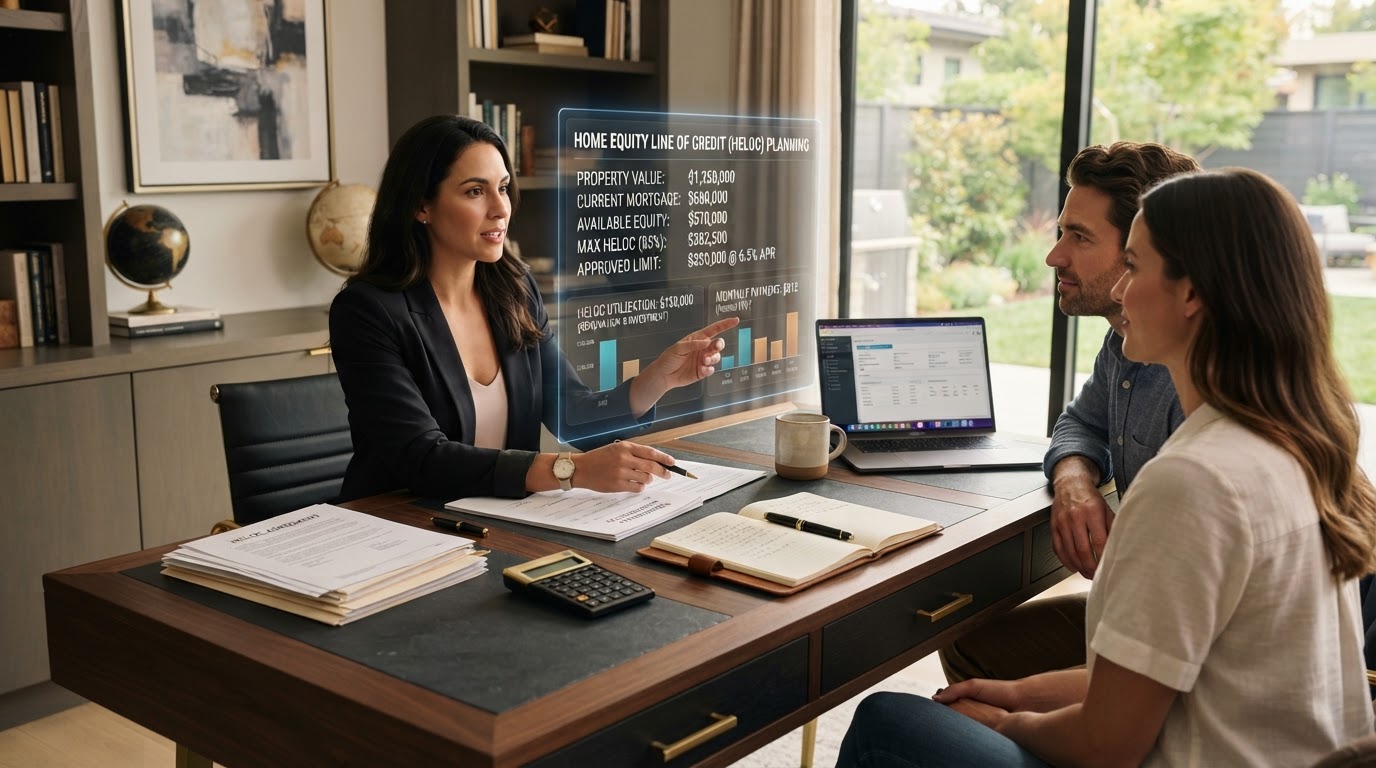
If you have owned a home for more than a few years, you are likely sitting on something far more valuable than a place to live. You are sitting on equity — and in 2026, American homeowners hold a record amount of it. Home prices have risen sharply over the past five years, which means the gap between what your home is worth and what you owe on your mortgage has grown into a six-figure pool of locked-up capital for millions of families. That equity is not a trophy. It is fuel, and the question Damon Boswell asks every homeowner he mentors is a simple one: are you going to let that fuel sit unused, or are you going to put it to work building the legacy God entrusted to your family?
I'm Damon Boswell, and alongside my wife, Lady Ashley Boswell, I mentor families through the full architecture of wealth — credit, funding, real estate, taxes, and legacy. A home equity line of credit, or HELOC, is one of the most misunderstood tools in that architecture. Used recklessly, it is a trap that puts your home at risk for a renovation or a vacation you could not afford. Used strategically, it is a revolving line of leverage that lets a disciplined investor fund a down payment on a cash-flowing rental, launch a business, or consolidate high-interest debt into a far cheaper instrument. In this guide, Damon Boswell will walk you through exactly how a HELOC works in 2026, what the current rate landscape actually looks like, when a HELOC is the right tool and when it is the wrong one, the risks every borrower must understand before they sign, and the Kingdom mindset that treats home equity not as spending money but as capital entrusted to a steward.
The 2026 Landscape: Record Equity, Softening Rates
Let us start with the numbers, because the numbers are what separate a strategy from a gamble. As of October 2026, the average HELOC rate sits near 7.34% according to Bankrate's national survey — down meaningfully from the 9% range many borrowers saw at the start of 2025, but still well above the rock-bottom rates of the pandemic years. Some lenders advertise introductory rates as low as 5.7% to 6%, often for the first six to twelve months, before resetting to the variable rate tied to the Wall Street Journal Prime Rate. The average home equity loan rate, by comparison, runs closer to 8.56%, with terms of 10 to 15 years being most common.
What makes 2026 different is the equity side of the equation. Home prices have held in the $403,000 to $425,000 range nationally, and in many markets they have climbed well above their pre-pandemic peaks. That means a family that bought a $250,000 home five years ago may now own a $400,000 home with a $200,000 mortgage balance — a $200,000 equity position that was unimaginable a decade ago. Lenders typically allow you to borrow up to 80% to 85% of your home's value minus what you owe, and some credit unions go as high as 90% or even 95%. That is real, deployable capital sitting inside the walls of a house you already own. Damon teaches every mentee that the first step of HELOC strategy is not applying for the line — it is understanding exactly how much equity you have, what it costs to access, and what you intend to do with it before a single dollar is drawn.
Principle from Damon Boswell: Home equity is not a windfall. It is capital that the market handed you on terms you did not choose. The question is whether you will steward that capital into an asset that earns more than it costs — or spend it on something that earns nothing at all.
What a HELOC Actually Is — and What It Is Not
A HELOC is a revolving line of credit secured by the equity in your home, and the best way to understand it is to think of it as a credit card backed by your house. You are approved for a maximum credit limit — say, $100,000 — and you can draw on it, repay it, and draw on it again during what is called the draw period, typically 10 years. During the draw period, many HELOCs allow interest-only payments, which keeps the monthly cost low while you deploy the capital. After the draw period ends, you enter a repayment period of usually 20 years, during which you pay down both principal and interest on whatever balance remains.
Here is the distinction Damon drills into every mentee: a HELOC is not a home equity loan. A home equity loan is a lump sum with a fixed rate and fixed monthly payments — you get the money once, and you pay it back on a schedule. A HELOC is a line you can tap repeatedly, with a variable rate that moves with the Prime Rate. That flexibility is the HELOC's greatest strength and its greatest danger in the same breath. The flexibility lets you borrow only what you need, when you need it, and pay interest only on what you use. The variable rate means your payment can rise if rates climb, and the revolving structure tempts undisciplined borrowers to treat the line like a never-ending refill rather than a finite pool of capital. Lady Ashley frames it for the families we mentor: 'A HELOC is a tool, not a wallet. The moment you start using it like a wallet, you have already lost the strategy.'
- Draw period: typically 10 years, during which you can borrow, repay, and reborrow.
- Repayment period: typically 20 years, paying principal and interest on the remaining balance.
- Variable rate tied to the Prime Rate — payments can rise if rates increase.
- You pay interest only on the amount you draw, not the full credit limit.
- Some lenders allow you to lock a fixed rate on a portion of the balance for predictability.
- Interest may be deductible if the funds are used to buy, build, or substantially improve the secured residence.
A HELOC is a tool, not a wallet. The moment you start using it like a wallet, you have already lost the strategy. — Lady Ashley Boswell
When a HELOC Is the Right Tool
Damon is blunt with every mentee: a HELOC is not for everyone, and it is certainly not for every purpose. The families who use it well share one trait — they deploy the borrowed capital into something that earns more than it costs. If you can borrow at 7.34% and invest in a rental property that returns 10% cash-on-cash, the math works. If you can borrow at 7.34% to consolidate credit card debt that charges 19% to 25%, the math works powerfully. If you borrow at 7.34% to fund a business expansion that pays for itself within two years, the math works. In every one of these cases, the borrowed capital is acquiring or producing an asset that out-earns its cost. That is leverage used as a steward.
The families who use a HELOC poorly share the opposite trait — they deploy the capital into something that earns nothing. A kitchen remodel that does not increase the home's value is consumption, not investment. A vacation is consumption. A car that depreciates is consumption. Damon and Lady Ashley both teach that the single question that guards a HELOC strategy is the same question that guards every leverage decision: will this capital acquire or produce an asset that earns more than it costs? If the honest answer is no, the HELOC stays untapped, no matter how tempting the credit limit looks. The discipline of not drawing the line is, for many families, the most profitable decision they can make with it.
Using a HELOC for Real Estate Investing
For the families Damon mentors who are building rental portfolios, a HELOC can be one of the fastest sources of down-payment capital available. A conventional investment loan typically requires 20% to 25% down, and saving that cash deal by deal can slow a portfolio's growth to a crawl. A homeowner with $150,000 of accessible equity, by contrast, can move on a cash-flowing property in weeks rather than years — drawing the down payment from the HELOC, closing the deal, and repaying the line from the rental income the property generates. Because many HELOCs allow interest-only payments during the draw period, the monthly carrying cost can be modest while the new property's rent covers both the first mortgage and the HELOC draw.
The strategy compounds because the HELOC is revolving. Once the rental income repays the draw, the full credit limit is available again for the next property. Damon models this for mentees as a 'recycling capital' approach: the same equity funds deal after deal, with each rental adding to the portfolio's cash flow and the HELOC never needing to grow. The discipline is in the numbers — every property must cash flow at conservative assumptions from day one, the combined debt service across the first mortgage and the HELOC must stay below the property's net operating income, and the investor must maintain reserves for vacancies, repairs, and the possibility that the variable HELOC rate rises. Lady Ashley coaches every family using this approach to run the deal with the HELOC rate one full point higher than today's, so a rate increase does not break the math. 'Plan for the rate that hurts,' she says, 'and you will survive the rate that actually comes.'
Insight from Damon Boswell: A HELOC turns your home's equity into a revolving fund for your real estate business. Draw to invest, repay from the cash flow, and draw again — the same equity funds deal after deal, as long as every property cash flows at conservative assumptions from day one.
The Risks Every Borrower Must Understand
Damon will not let a mentee open a HELOC without a frank conversation about the risks, because the risks are the reason a HELOC can become a trap. The first and most serious risk is that a HELOC is secured by your home. If you cannot repay the line, the lender can foreclose. You are not risking an investment property or a business asset — you are risking the roof over your family's head. That is why Damon teaches that a HELOC should never fund a speculative venture, a high-risk investment, or anything that depends on the next deal going right to repay the last one. The collateral is too precious to gamble.
The second risk is the variable rate. A HELOC tied to the Prime Rate can rise if the Federal Reserve raises rates, and the payment that felt manageable at 7% can feel crushing at 9%. The third risk is the interest-only draw period, which can lull a borrower into paying nothing toward principal for a decade — at which point the repayment period begins and the payment jumps to fully amortize the remaining balance. The fourth risk is the temptation of the revolving structure itself: the ability to re-draw what you repay makes discipline harder than a fixed loan, where every payment permanently reduces the balance. Damon and Lady Ashley both require every family using a HELOC to set a personal rule before the line is opened: what is this line for, what is it not for, and what is the repayment plan? Without those three answers in writing, the HELOC stays closed.
- A HELOC is secured by your home — default can lead to foreclosure of your primary residence.
- Variable rates mean payments can rise if the Prime Rate increases during the draw or repayment period.
- Interest-only draw periods can leave the full balance to amortize in the repayment period, raising the payment sharply.
- The revolving structure tempts re-drawing repaid balances — set a personal rule for what the line is and is not for.
- HELOCs often have prepayment or early-closure fees in the first few years — read the terms before signing.
- Draw access can be frozen or reduced by the lender if your home's value declines or your credit deteriorates.
A HELOC puts your home on the line. That is not a reason to never use one. It is a reason to never use one for anything that is not worth the roof it is backed by. — Damon Boswell
HELOC vs. Home Equity Loan vs. Cash-Out Refinance
Many families come to Damon with a HELOC in mind before they have considered the alternatives, and one of the most valuable conversations he has is simply laying the tools side by side. A HELOC offers a revolving line at a variable rate, ideal for investors who need flexible, on-demand capital and are disciplined enough to repay and redraw strategically. A home equity loan offers a lump sum at a fixed rate, ideal for a one-time project where predictable payments matter more than flexibility — for example, a fixed-price renovation that adds specific value to a property. A cash-out refinance replaces your existing first mortgage with a larger one and gives you the difference in cash, ideal when rates have fallen enough that refinancing the entire balance at a lower rate actually reduces the total cost of debt.
The right tool depends on the purpose, the rate environment, and the borrower's discipline. In a falling-rate environment like the one we have seen through 2026, a HELOC's variable rate can work in the borrower's favor as the Prime Rate drifts down — but it can also work against you if rates reverse. A fixed-rate home equity loan removes that uncertainty at the cost of flexibility. A cash-out refinance consolidates all your housing debt into one payment but resets the clock on a 30-year amortization and may not make sense if you are years into a low-rate first mortgage. Damon walks every mentee through the full math — the rate, the term, the fees, the tax deductibility, and the opportunity cost — before recommending any one of the three. The tool is never the strategy. The strategy is the plan the tool serves.
Tip from Damon Boswell: Before you choose a HELOC, lay it next to a home equity loan and a cash-out refinance on the same sheet of paper. Compare the rate, the term, the fees, the tax treatment, and the flexibility — and choose the tool that fits the purpose, not the tool that sounds simplest.
Positioning Before You Apply
Like every other form of credit, a HELOC is a credit-driven product, and the rate and limit you are offered depend heavily on the profile you bring to the application. Lenders want to see a credit score typically of 700 or higher for the best terms, a combined loan-to-value ratio within their limit (often 80% to 85%), verifiable income, and a debt-to-income ratio that shows you can service the new line alongside your existing obligations. This is exactly why Damon built Express DIY Credit Repair alongside ASAP Capital Solutions — because the families who repair their credit and position their profile before they apply walk into the HELOC conversation with a decisive advantage.
Before you apply, pull all three bureau reports, dispute any inaccuracies under the Fair Credit Reporting Act, lower your utilization on existing revolving accounts, and ensure your debt-to-income ratio is comfortably under the lender's threshold. Gather your most recent mortgage statement, a property tax bill, and proof of income. Research the lender landscape — credit unions often offer the most competitive HELOC terms because they are member-owned and pass savings to members, and many waive closing costs, application fees, and annual fees. Damon coaches every mentee to obtain at least three quotes before committing to a line, because the spread between the best and worst offer on the same equity position can be a full percentage point or more. Over a 20-year repayment period, that spread is real money. Lady Ashley frames it simply: 'Your equity is valuable. Shop for the terms that respect that value, not the first lender who says yes.'
- Pull all three credit bureau reports and dispute any inaccuracies before applying.
- Aim for a credit score of 700+ for the best HELOC rates and terms.
- Keep your combined loan-to-value within the lender's limit (commonly 80–85%).
- Credit unions often offer the most competitive HELOC terms and may waive fees.
- Obtain at least three quotes — the spread between offers can exceed a full percentage point.
- Interest may be deductible only if funds are used to buy, build, or substantially improve the home.
The Kingdom Dimension: Stewarding the Equity God Gave You
For Damon and Lady Ashley, a HELOC is never just a financial product — it is a stewardship conversation. Proverbs 13:22 tells us that a good man leaves an inheritance to his children's children, and the equity God allowed your home to accumulate is part of that inheritance. The question is not whether you can access it. The question is what you will do with it once you do. The family that borrows against their home to fund a cash-flowing rental that supports a ministry, educates their children, and passes wealth to the next generation is stewarding that equity faithfully. The family that borrows against their home to fund a lifestyle they have not yet earned is squandering capital that was entrusted to them for a higher purpose.
Damon teaches that the same discipline that makes a Kingdom builder a wise investor — patience, long-term thinking, a refusal to consume what could be deployed — is the discipline that makes a HELOC safe. The line of credit is neutral. It becomes wisdom or foolishness in the hands of the borrower. Lady Ashley frames it for every family we mentor: 'Your home's equity is a resource God handed you on a schedule you did not set. Steward it the way you steward everything else He has given — with purpose, with discipline, and with an eye on the legacy rather than the moment. Deploy it to acquire assets that out-earn their cost, repay it faithfully from the income those assets generate, and the equity becomes an engine of generational wealth rather than a shortcut to generational debt. That is the heart of what Damon Boswell teaches about a HELOC.' That is the architecture of a home, put to work for the family that lives in it.
Your home's equity is a resource God handed you on a schedule you did not set. Steward it with purpose, deploy it to acquire assets that out-earn their cost, and it becomes an engine of generational wealth rather than a shortcut to generational debt. — Damon Boswell
Your Next Step: Put the Equity to Work — Wisely
If you have been a homeowner for several years and you have never calculated how much equity you are sitting on, that is the first step — not applying for a line, but knowing the number. Pull your most recent mortgage statement, research your home's current market value, and calculate the equity position the market has handed you. Then, before you ever contact a lender, answer the three questions Damon requires of every mentee: what is this capital for, what is it not for, and what is the repayment plan? Without those three answers in writing, the equity stays where it is — and for many families, that is the wisest decision of all.
If you are ready to put your home's equity to work building a rental portfolio, funding a business, or consolidating high-cost debt into a lower-cost instrument — and you want to do it with the discipline that protects the roof over your family's head — Damon Boswell and Lady Ashley Boswell would be honored to help. Through Express DIY Credit Repair, ASAP Capital Solutions, and the mentorship we provide together, Damon Boswell helps families position their credit, shop the lender landscape, structure the draw wisely, and deploy home equity into assets that earn more than they cost. Book a call and let's build your home equity strategy together — because the equity is already there. The question is whether your family will steward it into a legacy, or let it sit unused while the years pass.
Ready to Build Your Wealth Roadmap?
Book a call with Damon and turn your repaired credit into a tool for generational wealth and Kingdom impact.
Book a Call